
Belfast Savers Told To Fix Four Common Tax Deadline Mistakes
As the end of the tax year approaches, a finance expert has warned that too many savers in Belfast are making simple errors that will affect their savings, costing them thousands in the long-term.
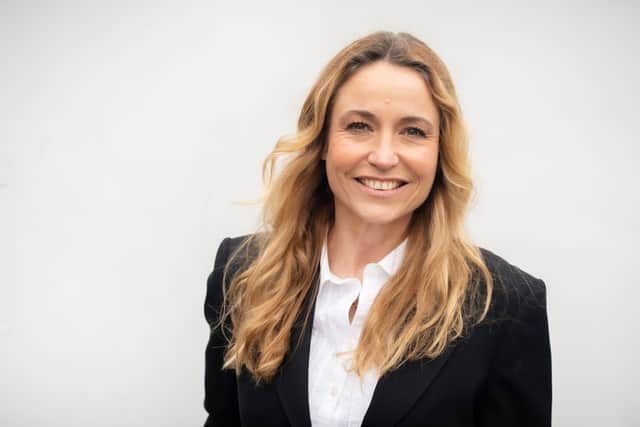
Antonia Medlicott, Founder and Managing Director of financial education specialists, Investing Insiders, has revealed four of the easiest mistakes people in Belfast make with ISAs towards the end of the tax year, and how to fix them with a handful of days to go.

Opening the wrong ISA and not receiving the benefits
Antonia says that despite there not being long until the ISA deadline, don’t make the mistake of choosing the wrong ISA for your financial goals.
She says: “For example, a Lifetime ISA may be best for those looking to purchase their first home or looking towards retirement, as it comes with a bonus of 25 per cent, but a harsh penalty if withdrawn for other reasons.
“For those looking to take money out sooner, then a Cash ISA may be better. Hugely competitive rates available ahead of the deadline, so take the time to compare them online. By rushing into the first one you see, you could cost yourself thousands of pounds in interest.”
Rushing an investment just to use the allowance
If you are pondering your investment strategy, Antonia explains that you don’t need to invest this money yet.
She says: “The worst thing you can do is make an impulse decision just to use the allowance. Start by putting the money into a Stocks and Shares ISA as cash and you can make a decision on where to invest it down the line, but this will mean it counts against this year’s allowance.
“Alternatively, or for anyone unsure of where to invest, there are ready-made portfolios available, but spend a couple of minutes checking performance to make sure it aligns to your risk level and goals.”
Paying costs needlessly
Antonia states that you should expect to pay some fees with your ISA, but strong returns can easily be wiped out by unnecessarily high platform fees that eat into your money.
She says: “See if consolidating your investments will cut costs, but if you do move provider, make sure this is done through an official ISA transfer rather than withdrawn first, as this will preserve the tax-free wrapper and your annual allowance.
“Compare the fees of your platform with those of others, as these can have a significant impact on how much you return. If your fund isn’t out performing the index it’s linked to, then you shouldn’t justify the charges and look to switch.
“If you invest small amounts and trade often, these fees will add up quickly if your platform charges every time you buy or sell. If this is your approach, ensure you’ve factored in trading costs when choosing a provider.”
Chasing quick win returns
Antonia explains that chasing quick results is a mistake that far too many make.
She says: “ISAs are not designed to make you thousands in just a few weeks, but see growth over time, so don’t put your money into one before April 5 and expect to see huge returns by the summer.
“Some people may have timed the market perfectly and made good money fast, but this is extremely difficult and unrealistic. For the majority, time in the market will beat timing the market for long-term gains.”
She adds: “When deciding where to invest money, a fund with excellent performance over the last few months will stand out, but this could be a slice of luck, so instead look for consistent performance over previous years.
“Particularly with recent issues around the world, markets have been more turbulent, so it’s vital to remember that past performance doesn’t guarantee future results.”
Finally, Antonia warns that whatever your plan is, do not forget the deadline.
She advises: “With the end of the tax year so close, the worst thing you can do is miss the deadline altogether. If you don’t use the ISA allowance by April 5, it will not roll over.
“Two key things to bear in mind when using an ISA are that it is protected from tax, so any money gained will not see an extra charge, and also that inflation is predicted to rise later this year, so money in a low-interest account will struggle to outperform an ISA that offers a healthy interest rate.”